Many small and medium-sized enterprises face the same issue: when owners request business data from finance, they receive standard financial statements—the balance sheet, income statement, and cash flow statement. While the data is complete and formatted correctly, owners often remain unsure how to proceed with decisions. This problem doesn't stem from a lack of financial expertise; rather, it arises from a structural mismatch between the design logic of traditional financial reports and the information needs for operational decision-making.
Addressing this pain point, we analyze the following four key issues.
1. Why Standard Financial Statements Fall Short of Owners' Needs
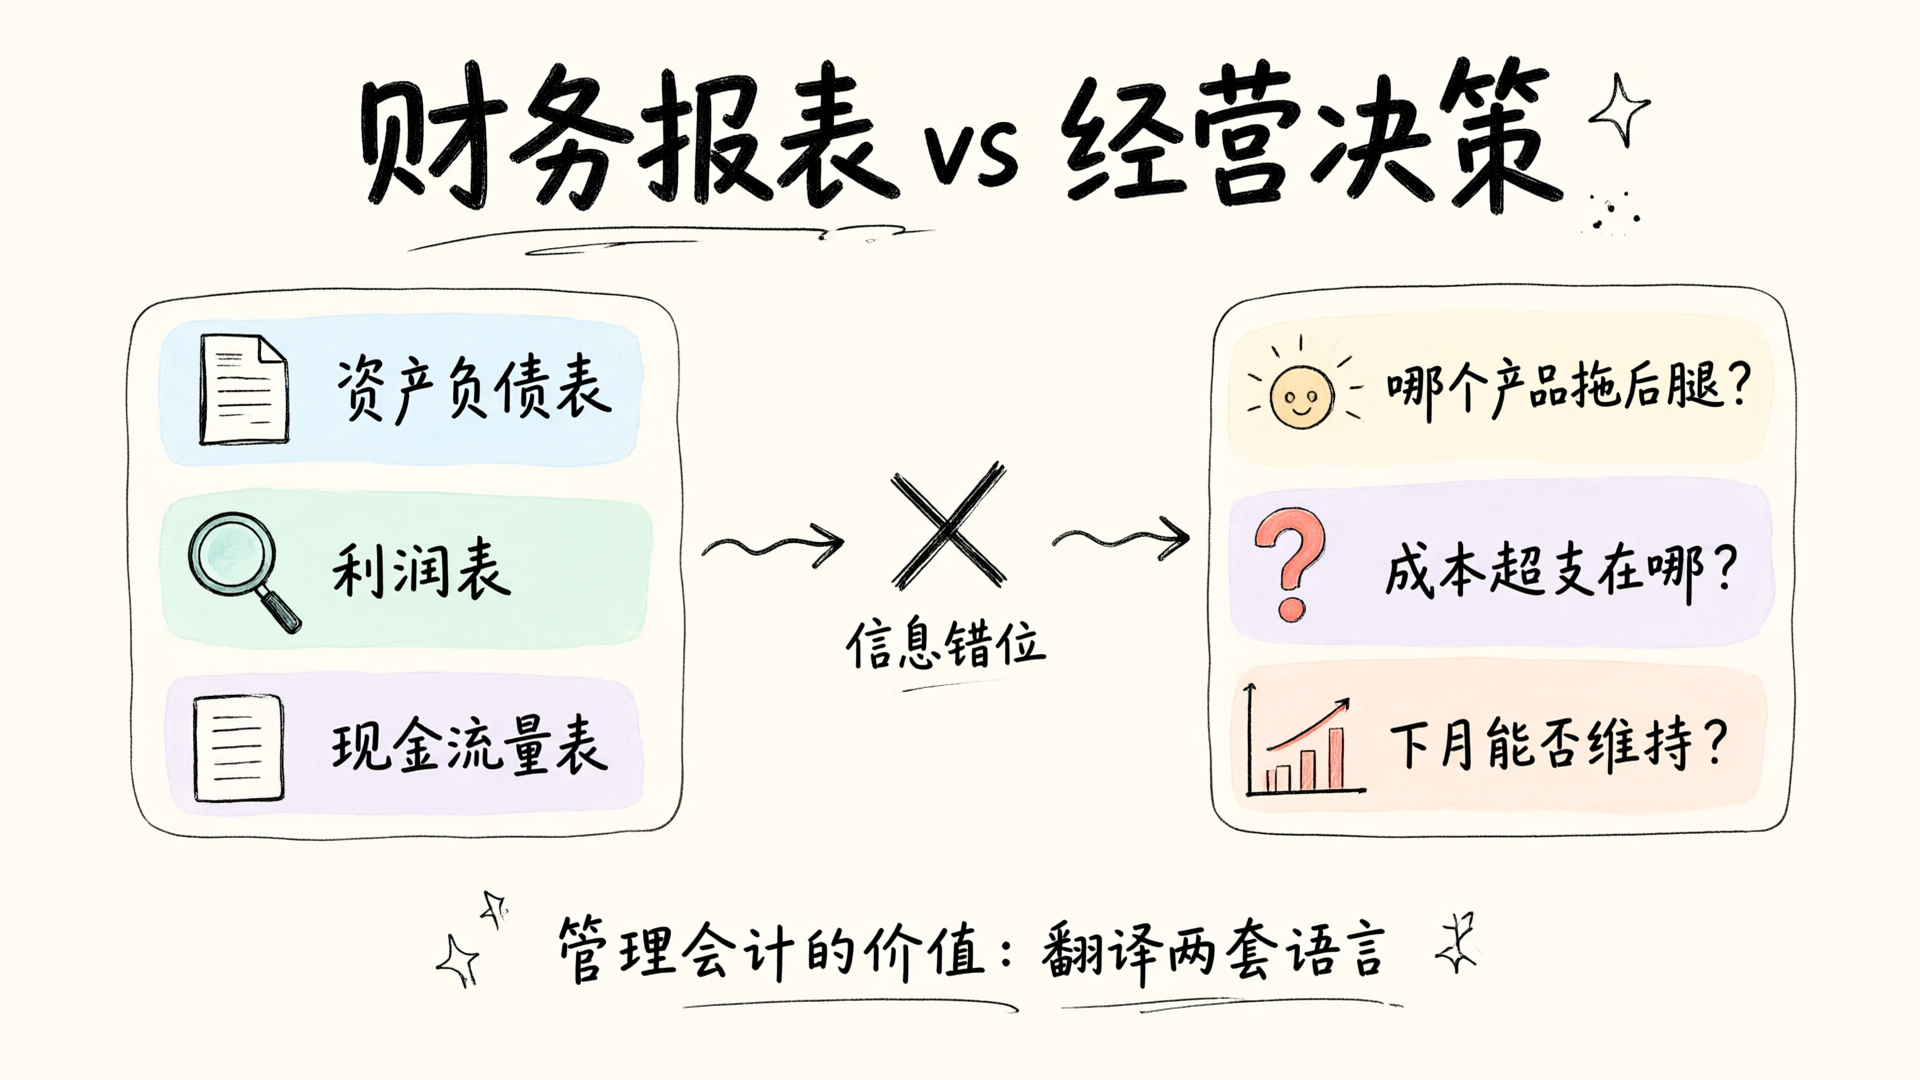
Standard financial reports serve external stakeholders—banks, tax authorities, and auditors. They follow accounting standards, emphasizing compliance and comparability, and record "what happened." Business owners need insights into "why it happened" and "what to do next" to make decisions.
The income statement tells the boss that profit this month is 50 ten-thousand, but what the boss really wants to know is: Of this 50 ten-thousand, how much comes from core operations? Which product line is underperforming? Where did cost overruns occur? Standard reports can't answer any of these. The reason is that traditional financial statements organize data by accounting categories, while business decisions require breaking down data by operational dimensions. Bridging these two ways of organizing information—this translation work—is the core value of management accounting.
II. What bosses truly want to see in reports
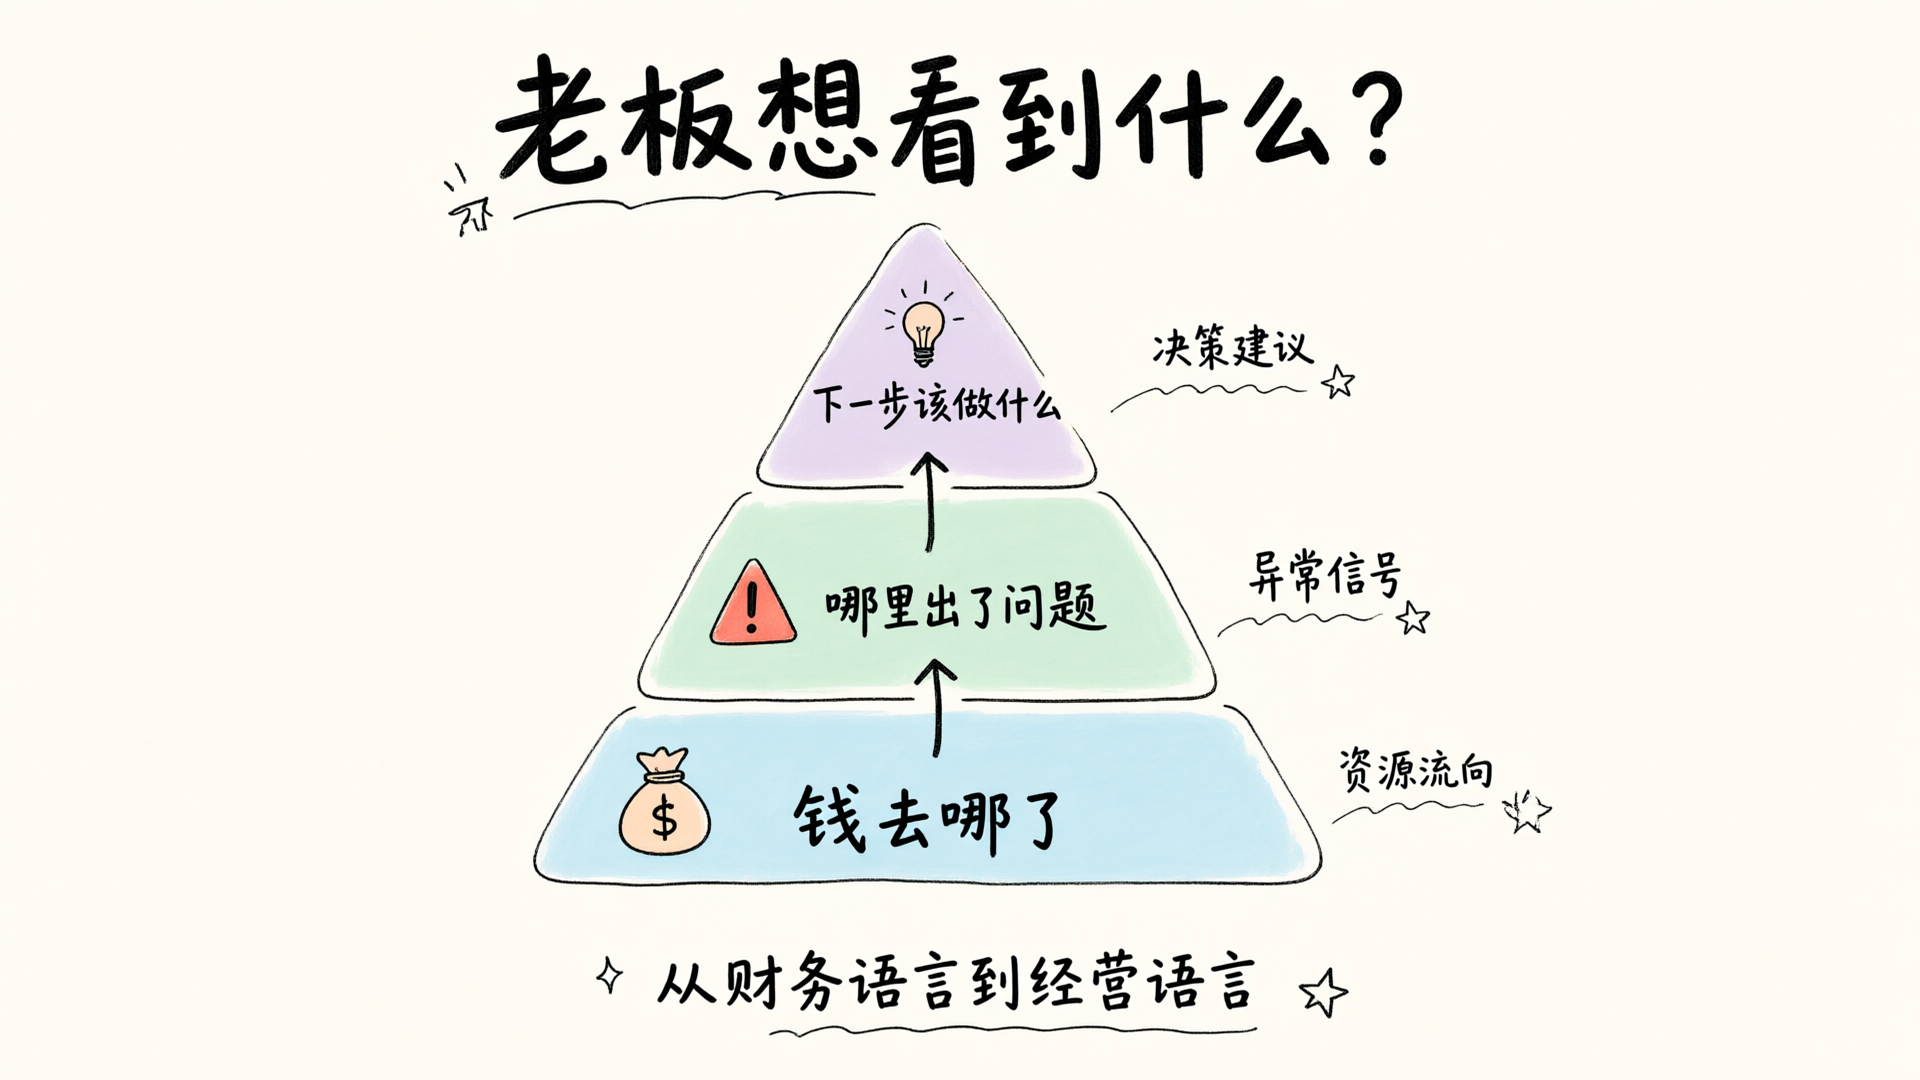
Based on our experience serving over 50 small and medium-sized enterprises, business owners' needs for operational reports can be categorized into three levels.
Layer 1: "Where did the money go?" — Not accounting-based expense categories, but business-level resource flow: Which customers, products, or stages consumed the most resources, and what was the return? Layer 2: "What went wrong?" — Which business segment saw margin compression? Which product line experienced slower inventory turnover? Executives need anomaly alerts, not exhaustive reports. Layer 3: "What's next?" — The purpose of a report isn't data display; it's actionable decision support.
These three layers of requirements are expressed in business language, not financial terminology.
III. What Core Modules Should Business Reports Include?
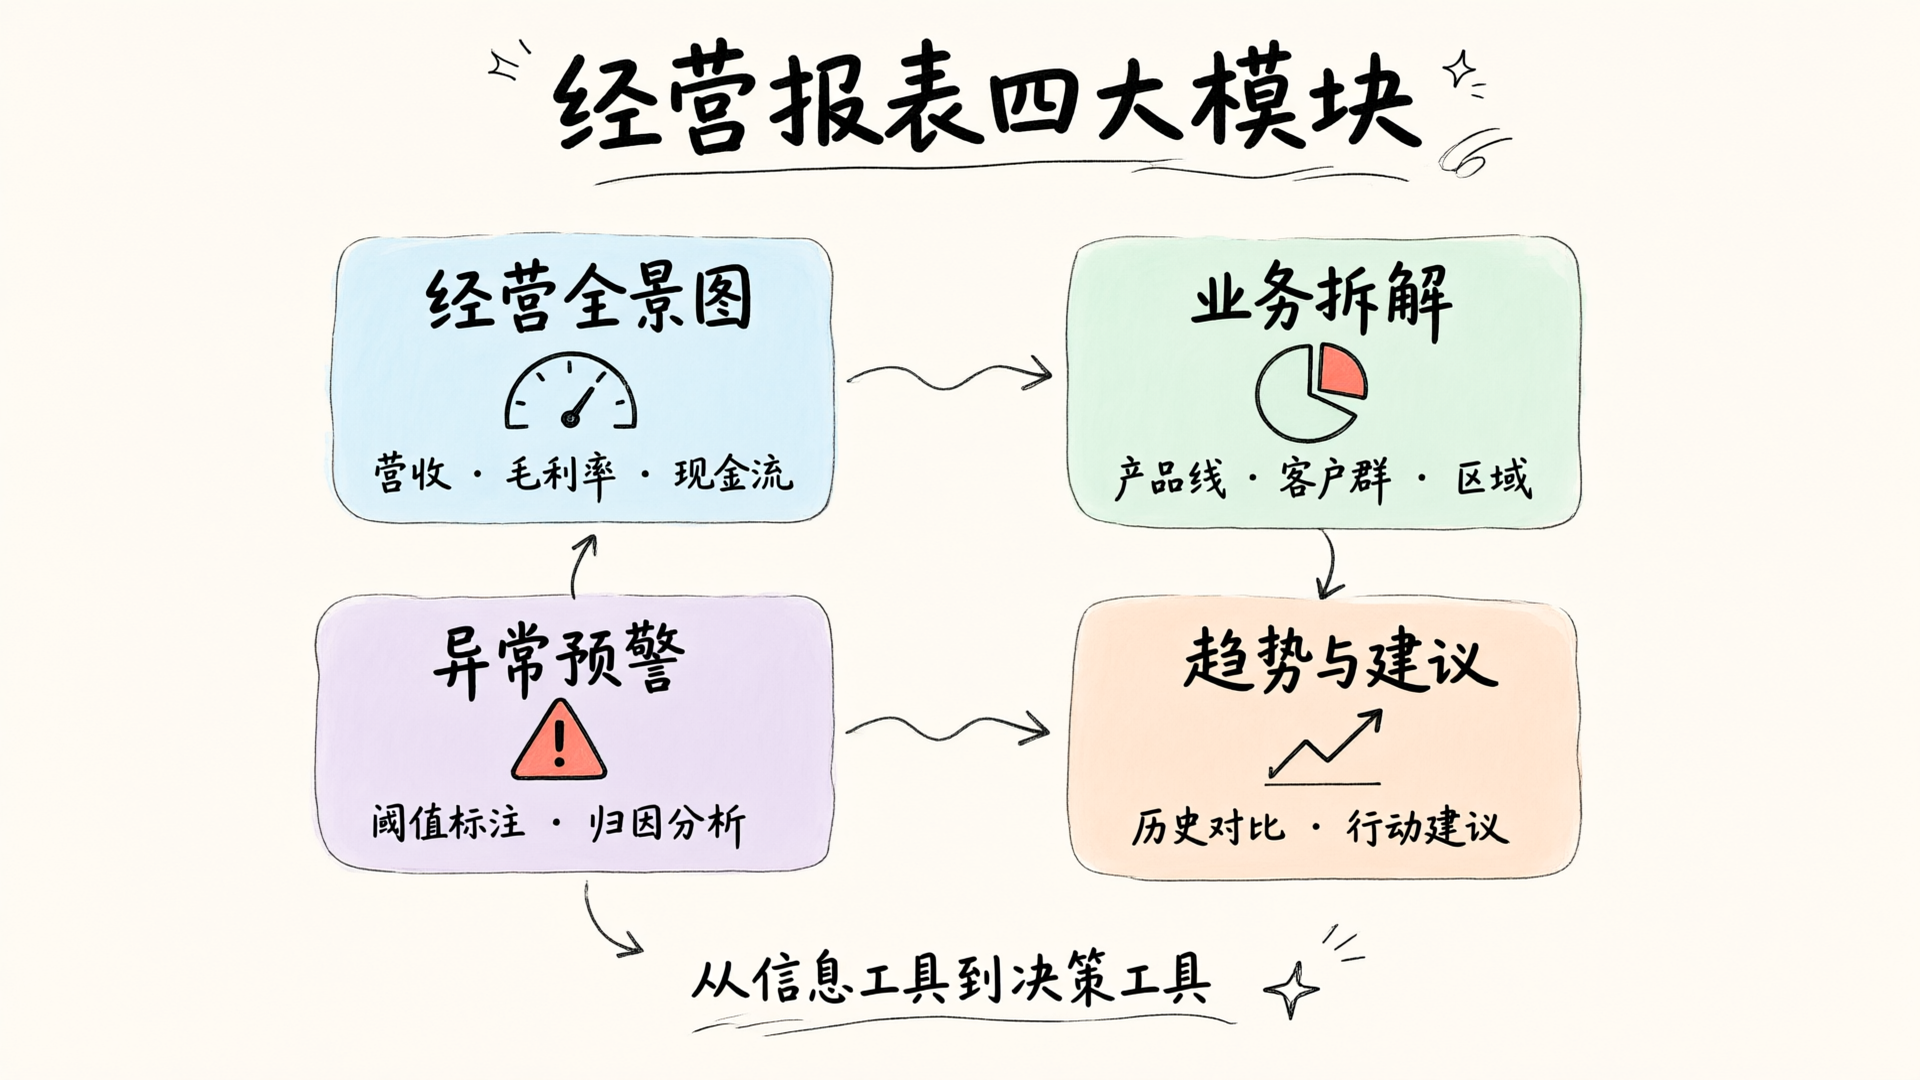
A set of business reports that executives can understand typically includes four core modules.
Business Overview: Display overall business performance using 3-5 core metrics—revenue, gross margin, net margin, cash flow, and days sales outstanding (DSO). Metric selection must align directly with the company's core business model. Manufacturers focus on capacity utilization and unit cost; e-commerce prioritizes average order value and repeat purchase rate; service providers emphasize employee productivity and customer retention.
Business BreakdownBreak down overall data by product line, customer segment, region, or channel so leadership can see the contribution and health of each business unit. The breakdown dimensions must align with the operational decision points your leader focuses on daily, not just accounting categories.
Anomaly AlertSet thresholds for key metrics to automatically flag deviations from expectations. For example, if a product line's gross margin falls below the baseline of 5 percentage points for two consecutive months, clearly highlight it in the report and provide an initial root-cause analysis.
Trends and RecommendationsCompare current data with historical periods and budget targets to show trends, and include actionable recommendations based on data analysis. This transforms the report from an information tool into a decision-making tool.
4. The report is ready—how do we ensure it drives decisions?
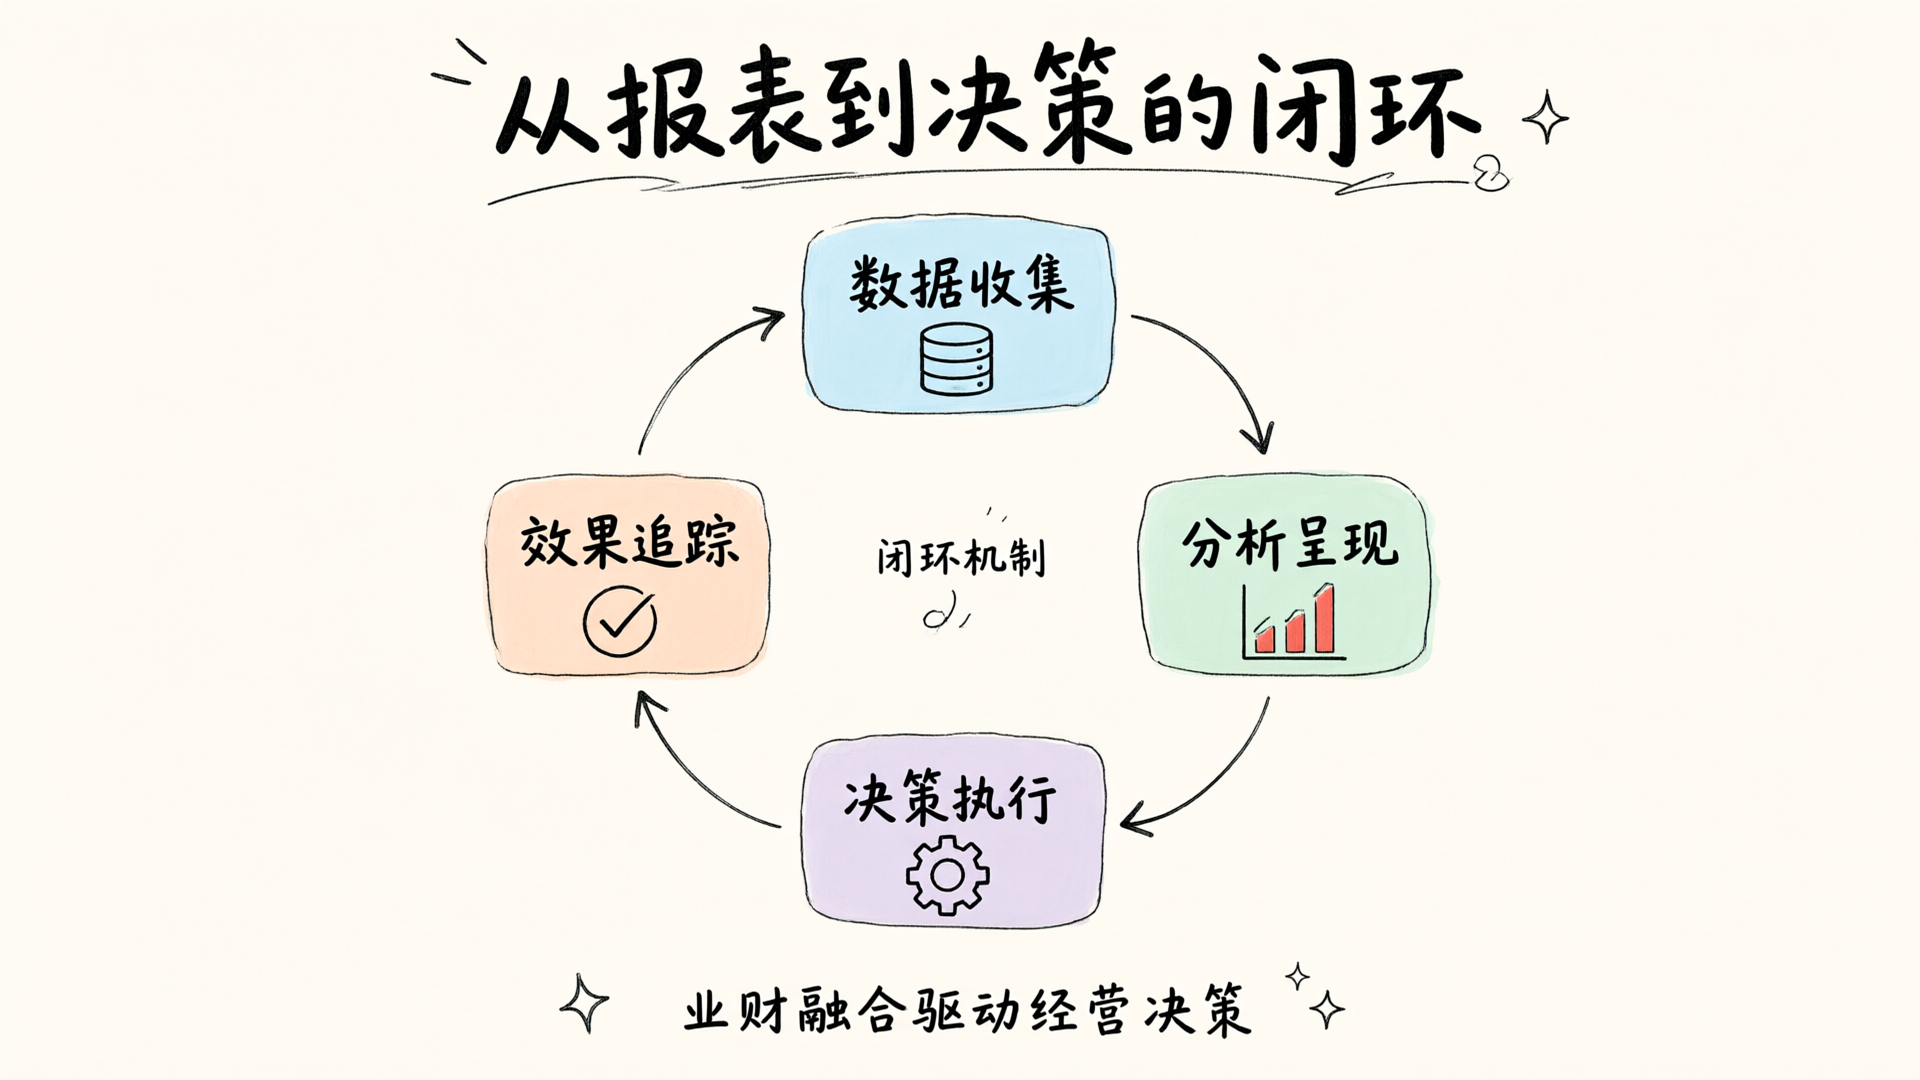
Report design is just the beginning. To truly unlock their value, you need a closed-loop system that covers data collection, analysis and visualization, decision execution, and outcome tracking.
We've observed that while many enterprises produce visually stunning reports, their decision implementation rates remain low. The root cause is a lack of alignment between reports and business actions. Key processes—such as who accesses the reports, which metrics they review, who responds to anomalies, and how follow-up outcomes are tracked—must be clearly defined.
The value of management accounting goes beyond designing a single report. It lies in connecting financial data, business logic, and management decisions through an integrated finance-business perspective. This is the methodology we've validated over 10 years of serving small and medium-sized enterprises: financial data only delivers true management value when embedded within operational contexts.